“We can hire an operator ourselves for $50 an hour. Why would we pay $70 for labour hire?”
For contractors managing tight margins, it is a reasonable question. However, comparing an employee’s wage with a labour hire charge leaves significant costs out of the calculation.
Superannuation, insurance, recruitment, payroll administration and protective equipment all affect the true cost of employment. Australia’s Payday Super changes also mean employers must consider when those costs leave their bank account.
When we put those expenses together, the difference can be much smaller than expected.
Start With the Same Assignment
Consider a machinery operator working 38 ordinary hours per week for 12 weeks—a total of 456 hours.
For this illustrative comparison, assume:
- Direct employment: $50/hour, including casual loading, plus superannuation.
- Labour hire: $70/hour, including employment on-costs, recruitment, agreed screening, payroll administration and agreed PPE.
- Both options exclude GST, overtime, penalties, allowances, travel and accommodation.
These figures are budgeting assumptions, rather than an award assessment or quotation. Actual employment requirements, insurance costs and agency inclusions must be confirmed.
As the direct employee is casual, annual leave and personal leave provisions have not been added.
The Apparent $9,120 Saving
Looking only at wages, the calculation appears straightforward.
Direct wages: 456 hours × $50 = $22,800.
Labour hire: 456 hours × $70 = $31,920.
That creates an apparent $9,120 saving from employing the operator directly.
But the $50 wage does not represent the employer’s complete cost. It also places responsibility for recruitment, employment administration and payment processing within the business.
Put the Other Costs Back In
Someone must advertise, answer enquiries, review resumes, interview applicants and check references.
Once the operator starts, payroll, superannuation, employee records and equipment still require attention.
Here is an illustrative allocation:
| Direct employment cost | Calculation or assumption | Total |
| Casual wages | 456 hours × $50 | $22,800.00 |
| Superannuation | 12% of wages | $2,736.00 |
| Workers compensation provision | 6% of wages | $1,368.00 |
| Public liability and other insurance allocation | 2% of wages | $456.00 |
| PPE and uniforms | 1.5% of wages | $342.00 |
| Payroll tax provision | Assumed 5% of wages plus super | $1,276.80 |
| Recruitment and candidate coordination | 18 hours × $80 | $1,440.00 |
| Pre-employment checks | Budget allowance | $350.00 |
| Routine payroll administration | 12 weeks × 0.5 hours × $60 | $360.00 |
| Additional super payment administration | 12 weeks × 0.25 hours × $60 | $180.00 |
| Employment records and employee queries | 3 hours × $60 | $180.00 |
| Total modelled direct employment cost | $31,488.80 |
Insurance percentages are budgeting allocations, not universal premiums. Payroll tax depends on applicable thresholds, exemptions and taxable wages.
Internal time should reflect the work attributable to this hire. Automated processes may reduce administration, while shared tasks should be allocated across employees.
Public liability cover may still be required when using labour hire. Only genuinely avoided or transferable insurance costs should be treated as savings. Site induction, supervision and competency verification also remain outside this comparison.
The $20 Gap Becomes Less Than $1
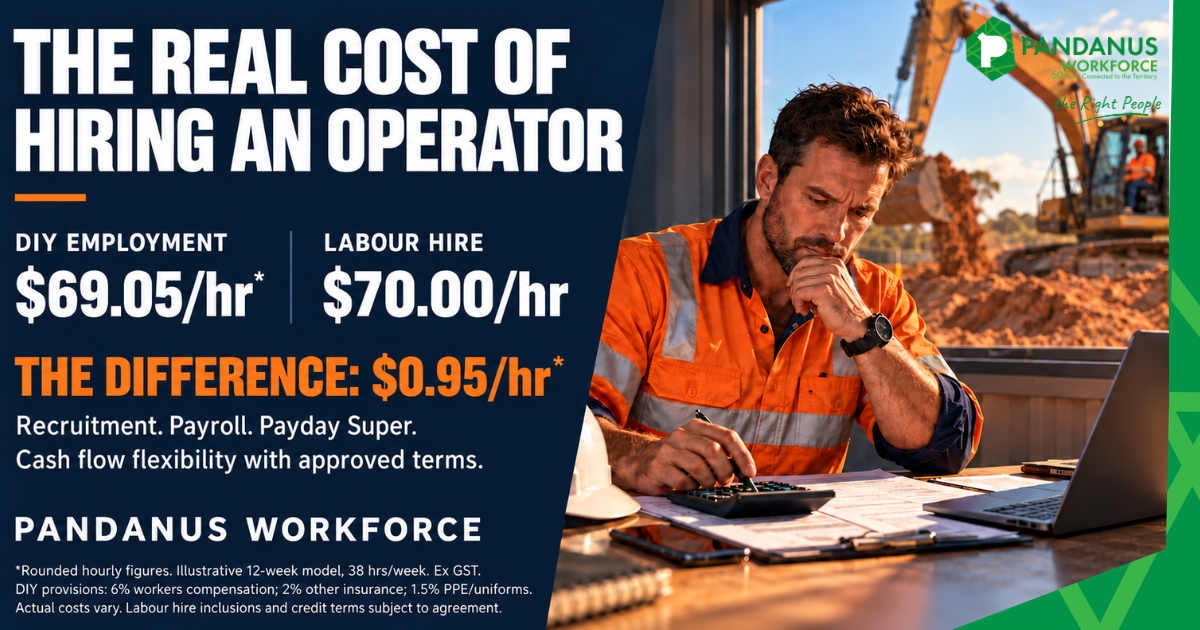
The modelled direct employment cost reaches approximately $69.05 per working hour.
Against labour hire at $70/hour, the difference is approximately 95 cents an hour.
Across the assignment:
| Comparison | Total |
| Modelled direct employment | $31,488.80 |
| Labour hire | $31,920.00 |
| Labour hire premium | $431.20 |
The apparent $9,120 saving has narrowed to $431.20 over 12 weeks.
At an internal management cost of $80/hour, approximately 5.4 additional hours of unbudgeted recruitment or administration would absorb that difference.
Payday Super Makes Timing Matter
From 1 July 2026, employers must pay super alongside wages, with contributions generally required to reach the employee’s fund within seven business days, subject to applicable exceptions.
For this operator, weekly gross wages are $1,900, with $228 in super.
Across ten equivalent operators, that becomes $19,000 in weekly gross wages plus $2,280 in superannuation.
The super cost is already included in the table. The change affects payment timing and processing rather than creating an additional contribution expense.
For contractors waiting on progress claims, earlier cash outflows can increase working capital pressure.
Where Labour Hire Can Help Cash Flow
Where the agency is the employer, it funds and administers its employees’ wages and super obligations. The client pays invoices under agreed terms.
For example, approved terms of 30 days from each weekly invoice can provide breathing room between workforce deployment and payment.
At $70/hour, one operator generates a $2,660 weekly invoice, excluding GST. Four weekly invoices total $10,640.
That illustrates potential supplier credit before invoices fall due. It is working capital support, not a saving, and depends on approved terms, invoice timing and credit limits.
What Is Reliable Support Worth?
No recruitment approach eliminates turnover, absences or unsuitable hires.
However, a trusted agency can help through candidate qualification, clear expectations, agreed checks and responsive communication when requirements change.
In this model, labour hire costs $431.20 more across 12 weeks. The commercial question is whether that support delivers greater value than the remaining premium.
At Pandanus Workforce, we encourage employers to compare the complete cost of workforce delivery—including internal effort and cash flow requirements.
Before comparing a $50 wage with a $70 charge, put every cost on the table.
Speak with Pandanus Workforce about a solution built around your project.
www.pandanus.au | 1800 845 133